



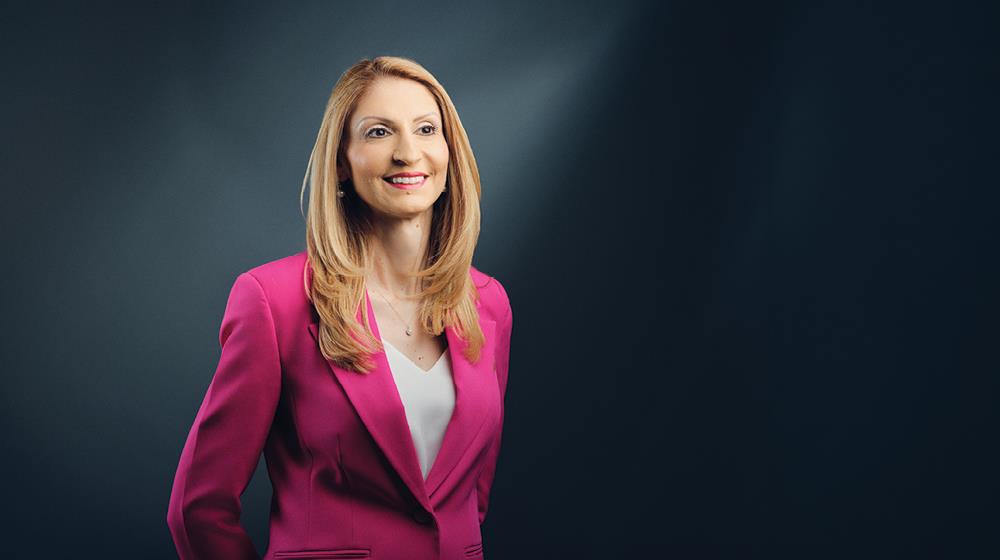
“Investment banking remains fundamentally a relationship-driven business. AI can help analyse information more efficiently, but building trust, understanding context and helping clients navigate complex situations remain deeply human responsibilities. In my team, we are already incorporating AI into a variety of workflows and processes,” Athena Theodorou, the Managing Director, EMEA Technology Investment Banking at UBS, suggests.
In an interview with GOLD magazine, Theodorou discusses the challenges facing Europe, the growing role of AI and how Cyprus can strengthen its position on the global technology map.
On your journey from Cyprus to leading technology investment banking across EMEA at UBS, what experiences have shaped your leadership style?
I grew up in Cyprus before moving to the United States to study Economics. Growing up on a small island taught me resilience, adaptability and the importance of creating opportunities rather than waiting for them. That mindset of asking “how can this be done?” rather than “why can’t it be done?” has stayed with me throughout my career. My career began at the Federal Reserve Bank of the United States in economic research, where I gained valuable insight into how macroeconomic policy influences businesses and global financial markets. I then moved into corporate finance and M&A at Deloitte, qualifying as a Chartered Accountant, before joining Morgan Stanley, where I spent more than a decade advising technology companies across EMEA. In 2022, I joined UBS, where I now lead software coverage within EMEA Technology Investment Banking. Technology banking requires continuous learning and I have had a front-row seat to major shifts in the sector, from cloud computing and software-as-a-service (SaaS) to fintech, digital transformation and now artificial intelligence. At the same time, investment banking is a “people business.” While technical expertise and strategic insight are important, this is fundamentally a relationship- and trust-driven profession. The most valuable advisory service is helping clients see risks, opportunities or strategic alternatives that they may not have fully considered themselves. As a leader, I have tried to combine high standards with curiosity, collaboration and accountability. I believe in creating an environment where people are empowered to challenge assumptions and think independently. Banking is ultimately a team sport and the best outcomes come from talented people working together around a shared objective.
Do you believe Europe is losing the tech and innovation race to the US and, increasingly, to Asia?
I would push back slightly on the idea of a single “race”, but Europe clearly faces challenges in building and scaling global technology champions. The issue is not a lack of innovation: Europe has exceptional universities, engineers, research capabilities and entrepreneurs. The real challenge is turning innovation into scale. The US benefits from significantly deeper capital markets, greater access to growth funding and a large, unified domestic market. Europe remains more fragmented, with companies navigating different regulatory regimes, legal systems and capital markets. Policy has an important role in addressing this while maintaining Europe’s strengths in trust and consumer protection. But capital and regulation are only part of the answer. Mindset matters too. European founders need to think globally from day one, building businesses for international markets rather than individual countries. I remain optimistic about Europe’s prospects. Personally, I would like to see more European technology companies scale, remain headquartered and ultimately list in Europe, not because they have to but because Europe is genuinely the best place to build a global champion.
Has geopolitics become as important as financial analysis in tech investment banking?
Geopolitics has always influenced markets, investment decisions and corporate strategy. What has changed is the frequency, magnitude and unpredictability of geopolitical and policy developments, and the speed at which they can affect businesses and global supply chains. Technology has become one of the primary arenas through which geopolitical competition is playing out. Today, AI, semiconductors, cybersecurity, data sovereignty and critical infrastructure sit at the intersection of economics, national security and public policy. What makes this particularly relevant is the degree of interconnectedness across the global economy. A company does not need to operate directly in a geopolitically sensitive sector to be affected. For example, a software company serving the automotive industry may have no direct exposure to export controls or tariffs. However, if automotive manufacturers are affected by supply-chain disruptions or changes in industrial policy, those effects can ultimately influence technology spending and growth prospects. Increasingly, it is these second- and third-order impacts that need to be understood. Financial analysis remains fundamental. Yet today, we also need to consider regulatory approvals, foreign investment screening, supply-chain dependencies, cybersecurity requirements and the broader policy environment. What makes the current environment particularly interesting is that, despite this uncertainty, parts of the market continue to place very high valuations on long-term technology themes, particularly artificial intelligence.
How is AI changing the way investment bankers work?
Investment banking remains fundamentally a relationship-driven business. AI can help analyse information more efficiently but building trust, understanding context and helping clients navigate complex situations remain deeply human responsibilities. In my team, we are already incorporating AI into a variety of workflows and processes. It is helping improve productivity across activities such as research, information synthesis, financial modelling, data analysis and document review. In many respects, the greatest benefit is not simply efficiency but the ability to focus more time on helping clients navigate increasingly complex strategic and financial decisions. It is important to separate the technology itself from the market excitement surrounding it. There is little doubt that AI is a genuinely transformative innovation. What feels different from previous technology waves is that the improvement in capabilities, the speed of adoption and the breadth of potential applications are occurring at an unprecedented rate. AI is creating opportunities on two fronts: companies are embedding it into products and services to drive growth while also using it internally to improve productivity and efficiency. The challenge for investors is that both impacts are still evolving. Assessing future growth rates is becoming more complex but so is understanding what sustainable margins will look like once the costs of AI investment and the benefits of AI-driven efficiencies are fully reflected. Periods of transformational innovation tend to attract significant amounts of capital and investor enthusiasm. Over time, attention shifts from potential to proof and valuations become increasingly linked to evidence of adoption, monetisation and sustainable economics. The question is not whether AI will create value. It unquestionably will. The real question is who captures that value and how defensible that position ultimately proves to be.
How different do you think technology investment banking will look five years from today?
Technology investment banking is already changing. Many tasks that used to be highly manual are becoming much faster. That does not make the role of the banker less important; the fundamentals of the profession remain the same: trust, judgement, strategic advice and long-term relationships are still at the heart of the business. What is changing is the standard of what clients expect. Information itself is becoming more accessible and many clients are increasingly sophisticated in how they use data and technology. Private equity firms, for example, are using AI and advanced analytics to identify, analyse and track potential investments with a level of sophistication that would have been much harder to achieve a few years ago. As a result, advisers cannot rely simply on providing information or standard analysis. We need to bring insight, but also creativity: original ideas, thoughtful strategic alternatives and perspectives that clients may not have considered themselves.
What sectors within technology are currently attracting the most investor interest in EMEA and which do you think are still undervalued?
There is still a significant amount of capital looking to be deployed in the technology sector, across both financial and strategic acquirers. Investors remain enthusiastic about technology and innovation, although they are becoming increasingly selective. Broadly speaking, many of the themes attracting attention in EMEA are similar to those we see in the United States, even if some regional nuances exist. Strong interest extends across the entire AI ecosystem, from foundational model developers, such as Mistral, to the infrastructure required to support AI adoption, including semiconductors, compute capacity and data centres, as well as the applications being built on top of those technologies. One of the clearest investment themes emerging from AI is the growing importance of digital infrastructure. Alongside demand for compute and connectivity, Europe is seeing increased focus on cloud sovereignty, data sovereignty and control over critical digital infrastructure. Cybersecurity continues to attract significant investor interest, while we are also seeing considerable interest in frontier technologies, particularly defence technology, automation, robotics and advanced engineering applications. Defence and security-related technologies have become much more prominent investment themes in recent years, reflecting broader shifts in geopolitical priorities, sovereign investment programmes and government spending patterns. Advances in robotics, autonomous systems and what is often referred to as “physical AI” are creating new opportunities across manufacturing, logistics, industrial automation and defence applications.
Within software, the picture is especially interesting. AI-native applications such as Pennylane, Legora and a number of newer software businesses are attracting substantial investor attention and, in many cases, commanding very high valuations. At the same time, one of the central debates in software today is AI defensibility. Investors are increasingly focused on understanding which businesses become stronger as AI capabilities become more broadly available and which become more vulnerable. The companies that continue to command premium valuations tend to be those with durable moats, whether through proprietary data, deep workflow embeddedness, strong customer relationships, network effects or other forms of differentiation that are difficult to replicate. The second debate is around long-term economics: how AI will affect future growth rates, pricing models, pricing power, margins and the ability to monetise new capabilities. As a result, investors are increasingly assessing software businesses on a case-by-case basis rather than treating the sector as a single category. Parts of the market continue to focus on disruption risk, while underappreciating the resilience of certain mission-critical software categories, particularly those embedded in critical workflows such as accounting, tax, payroll and specialised industry software.
Cyprus has been trying to position itself as a growing tech and startup hub in recent years. Do you think that international investors actually notice Cyprus or does the country still struggle for visibility?
International investors are certainly paying more attention to Cyprus today. We have developed a much stronger technology ecosystem, attracted international talent and businesses and established ourselves as a credible destination for companies looking to build and scale. The challenge is more about visibility. International capital often follows scale and familiarity. Investors tend to spend most of their time looking at ecosystems that have already produced multiple globally recognised success stories. Cyprus is still earlier on that journey. What is sometimes overlooked is that there are already a number of technology companies operating from Cyprus that have achieved significant international scale across sectors such as fintech, digital health and gaming. In many cases, these companies are simply not as well known internationally as the scale of their operations would justify.
The next step is to ensure that more of our success stories become visible internationally and that Cyprus becomes known as a place where globally competitive technology companies can be built and scaled.
If you were advising Cyprus on one bold move to attract more global technology investment over the next decade, what would it be?
It would be to position Cyprus around a small number of technology areas where we have genuine structural strengths and can build international recognition over time. Fintech and payments infrastructure would be one obvious example, given both our established financial services ecosystem and the growing number of technology companies in the sector that are successfully scaling from Cyprus. Maritime technology is another. I would also include AI-enabled business services, which build naturally on the country’s heritage in international services, trust, corporate and fund administration.
Finally, I believe there is a significant opportunity to engage more systematically with the Cypriot diaspora: an extraordinary global network of professionals, entrepreneurs, academics and investors, many of whom occupy influential positions in leading organisations around the world. Harnessing that network more effectively could become one of Cyprus’ most powerful competitive advantages over the coming decade.
This interview first appeared in the September edition of GOLD magazine. Click here to view it.